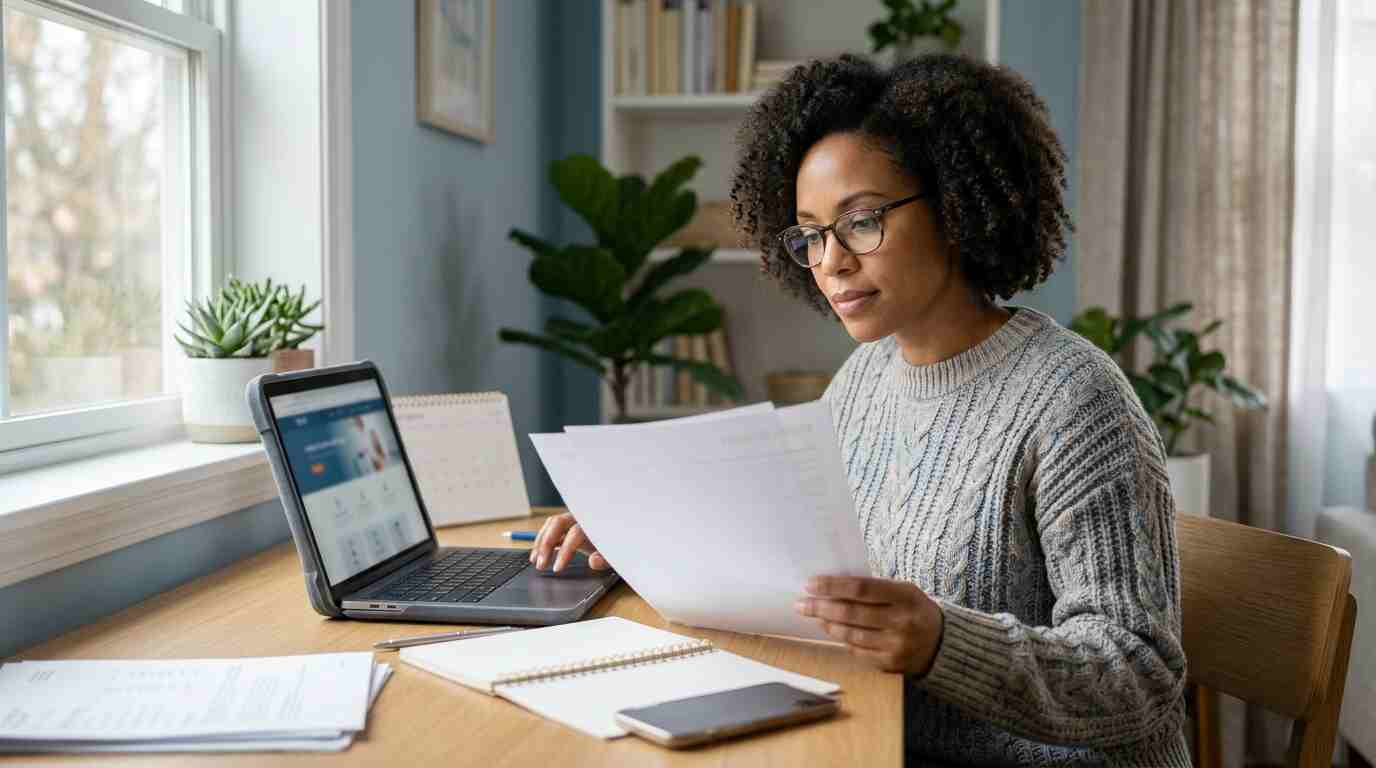
- Cetagory Blog Out-of-Network Healthcare Costs: What to Check Before an Appointment
- Piksla
Understanding out-of-network healthcare costs can help you make a more informed choice before planned care. The rules depend on your insurer, policy, provider, and location. This guide explains the questions to ask without assuming that every plan handles out-of-network care in the same way.
What Does “Out of Network” Mean?
Many health insurance plans have arrangements with particular doctors, hospitals, and other healthcare providers. Those providers are commonly described as “in network.” A provider without the relevant arrangement for your specific plan is “out of network.”
The phrase “specific plan” matters. A clinic may work with an insurance company but not participate in every policy that company offers. Similarly, a doctor may see patients at several facilities with different billing arrangements. Ask about your exact policy and the location where you will receive care.
Some plans offer benefits for certain out-of-network services. Others offer limited benefits or none for planned out-of-network care. Your policy documents and insurer can tell you which rules apply to you.
Why Can Out-of-Network Healthcare Costs Be Higher?
When a provider is in network, the provider and insurer may have agreed on how covered services will be priced. That arrangement may not exist for an out-of-network provider. Your plan might also require you to pay a different deductible, copayment, or percentage of the cost.
Another possible expense is the difference between what a provider charges and the amount your insurer recognizes for a service. Whether you can be charged that difference depends on your policy and applicable rules. Ask the insurer and provider how they would handle it instead of assuming that your usual copayment is the most you could owe.
For example, imagine that a specialist quotes a fee for a planned consultation. Your insurer says it covers some out-of-network consultations, but calculates its payment using a different amount. The insurer’s share may therefore be smaller than you expect. The example illustrates a possibility, not a formula that applies to every policy.
Check the Doctor and Facility Before Booking
If you are looking for a clinician, you can explore doctor profiles on SebaMedi by specialty or location and make a list of people to contact. Confirm appointment information with the provider. Then ask both the provider and insurer whether that doctor participates in your exact plan at the location you intend to visit. A directory profile does not verify insurance participation.
For hospital care, check the facility as well as the doctor. If your planned care may involve other professionals or a separate diagnostic center, ask who will provide those services and how they may be billed. You might not be able to identify every person involved in advance, but asking can help you understand the likely costs.
Record the date of your calls and any reference number the insurer provides. If your appointment location changes, confirm the network details again.
Ask for an Estimate You Can Actually Use
Before planned care, ask the provider for an estimate of its charges and what services the estimate includes. Is it only for the consultation? Could tests, medicines, a procedure, or a facility fee be billed separately?
Share the proposed service and provider details with your insurer. Ask whether the service is covered, whether out-of-network benefits apply, and how your share would be calculated. Also ask if a referral or prior authorization is required under your policy.
Neither the provider’s estimate nor the insurer’s response can predict every detail of a future bill. Together, though, they can show which charges you still need to investigate before making a decision.
What If Your Doctor Leaves the Network?
Network arrangements can change. If a doctor you already see is no longer in your plan’s network, contact the insurer before your next planned visit. Ask when the change takes effect, what an appointment would cost afterward, and which alternatives are available.
If you are receiving ongoing treatment, explain your situation rather than simply requesting another doctor’s name. Ask whether any policy terms or local rules address a transition in care. Your clinician can help you understand the medical considerations involved in changing providers; your insurer can explain the coverage options.
Keep notes about both conversations. That makes it easier to compare your options without relying on memory during an already stressful time.
Are Emergency Visits Handled the Same Way?
Do not delay seeking urgent medical help to check a provider’s network status. Emergency care may be subject to different insurance rules and legal protections from planned appointments. Those protections vary by location and type of coverage.
Once immediate care is being addressed, ask the insurer what information it needs and how the claim will be handled. Keep copies of any documents you receive from the hospital and insurer. Avoid applying an answer about a routine appointment to an emergency bill, or the other way around.
How to Review an Unexpected Bill
If a bill is higher than you expected, compare it with the provider’s itemized bill and your insurer’s explanation of benefits, if one is available. Check which services were billed, which provider supplied them, what the insurer processed, and what the bill says you owe.
Look for simple issues first. Was the correct policy information used? Is the provider or facility listed as you expected? Was a service billed twice? Contact the provider’s billing office or insurer for an explanation of anything you do not understand.
If you believe the claim was processed incorrectly, ask the insurer how to request a review or appeal under your policy. If you think a billing protection may apply where you live, ask the appropriate insurer or consumer assistance service about the steps available to you. Keep the bill, related correspondence, and notes from your calls together.
Five Questions to Ask Before Planned Care
- Is this doctor in network for my exact policy at this location?
- Is the facility in network, and might anyone bill separately?
- Does my plan cover this service if a provider is out of network?
- What deductible, copayment, or other share might I pay?
- Can the provider and insurer give me estimates in writing?
These questions take time, but they can reveal an important difference between two appointments that otherwise look similar. If an answer is unclear, ask the insurer to explain it using the provider and service you are considering.
Choose With a Clearer View of the Cost
An out-of-network provider may still be the person you decide to see. The useful step is knowing how your policy treats that choice before receiving planned care. Verify the provider and facility, ask about the complete set of likely charges, and keep written answers where possible.
When you understand what the insurer may pay and what could remain your responsibility, you can make a decision that fits both your healthcare needs and your budget.
- Prescription Drug Insurance Coverage: Questions to Ask Before You Fill a Medicine
-
 Health - 02:59:35pm 26-09-2026
- Out-of-Network Healthcare Costs: What to Check Before an Appointment
-
Health - 02:45:21pm 26-09-2026
-
 Blog
What Is the Best Cheap Car Insurance for Young Drivers
-
 Blog
Best Car Insurance for Electric Vehicles (EVs): Complete Guide for 2026
-
 Blog
Long Term Car Rental Discounts: The Complete Guide to Saving Big on Extended Rentals
-
 Blog
Best Car Insurance for Families with Young Drivers
-
 Blog
Health Insurance Waiting Period: What You Should Know Before Buying a Policy